The terrace next door
Demolishing a house between two older terraces, a contractor's work is blamed for cracking in both neighbours' walls. Whether the policy responds depends on its vibration and removal of support terms.
Understand the cover demolition contractors commonly use, what clients and sites ask for, and when it gets more complicated.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.
The short answer
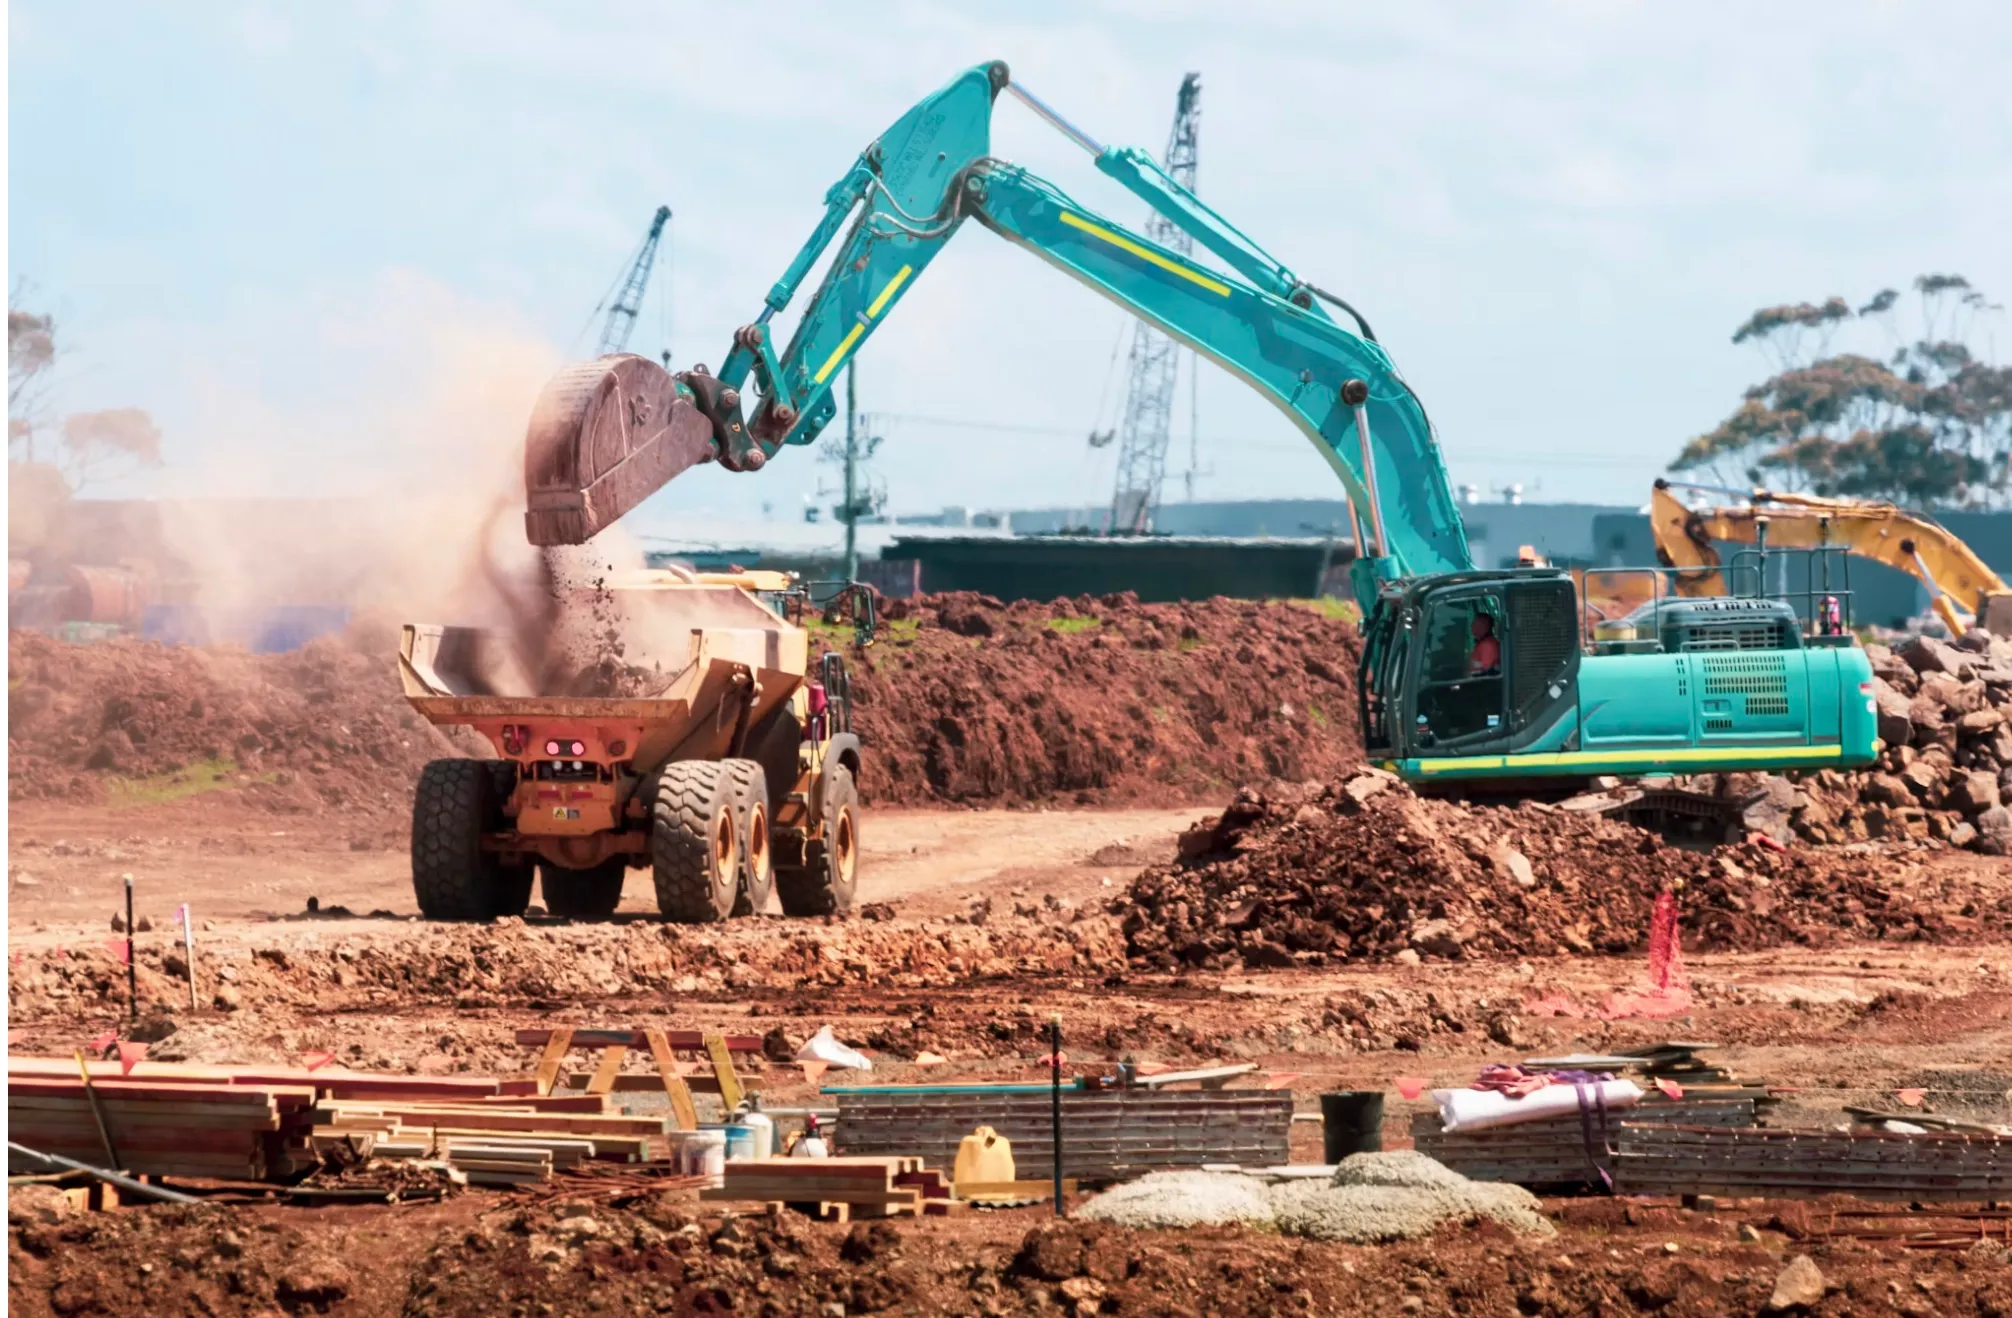
Demolition contractors in Australia usually need public liability insurance, often $20 million, plus plant, vehicle and tools cover. Demolition is one of the hardest activities to insure because of collapse, vibration damage to neighbours, dust and asbestos. Many mainstream insurers decline it, so specialist insurers are common.
Common cover
Most demolition contractors build their insurance from a few separate policies. These are the ones that come up most, and why they matter for this kind of work.
Covers damage to neighbouring buildings and injury to the public. Vibration and removal of support terms are critical for demolition.
Excavators, breakers, loaders and attachments.
Tippers and trucks carting waste.
Saws, breakers and portable equipment.
When it gets harder
Strip-out of an internal fit-out is very different from demolishing a building next to occupied homes. These are the main differences.
Damage to neighbouring structures from vibration or loss of support is a core demolition risk and is often excluded from standard policies.
Asbestos is generally excluded from public liability. Licensed removal needs specialist cover and licensing.
Larger structures need engineered methods and are a narrower market for insurers.
Internal strip-out is usually easier to insure than structural demolition, but it still needs to be declared accurately.
Illustrative examples
These are illustrative examples, not real clients, showing how the work changes the insurance.
Demolishing a house between two older terraces, a contractor's work is blamed for cracking in both neighbours' walls. Whether the policy responds depends on its vibration and removal of support terms.
During a strip-out, a crew finds asbestos not identified in the survey. Work has to stop, and standard public liability won't cover asbestos-related claims.
Cost
These factors drive demolition premiums.
| Factor | Impact | Why it matters |
|---|---|---|
| Type of demolition | Major | Strip-out, residential, commercial and structural demolition are rated differently. |
| Proximity to other buildings | Major | Urban sites close to neighbours carry more risk. |
| Height of structures | Major | Multi-storey demolition narrows the market. |
| Plant fleet value | Moderate | Affects plant and equipment premiums. |
| Claims history | Major | Property damage claims weigh heavily. |
Common questions
Demolition carries a high chance of damage to neighbouring property and injury to the public. Many mainstream insurers won't cover it, so it is usually placed with specialist insurers.
Generally no. Asbestos is a standard exclusion. Licensed asbestos removal needs specialist insurance.
Often not unless the policy specifically includes it. Vibration and removal of support are among the most important terms to check for demolition.
This page is general information only. It does not take into account your objectives, financial situation or needs, and it is not a recommendation to buy any insurance product. Always read the policy wording and, where applicable, the Product Disclosure Statement.
Request a quote
Tell us your trade or industry. It only takes a moment to get started.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.