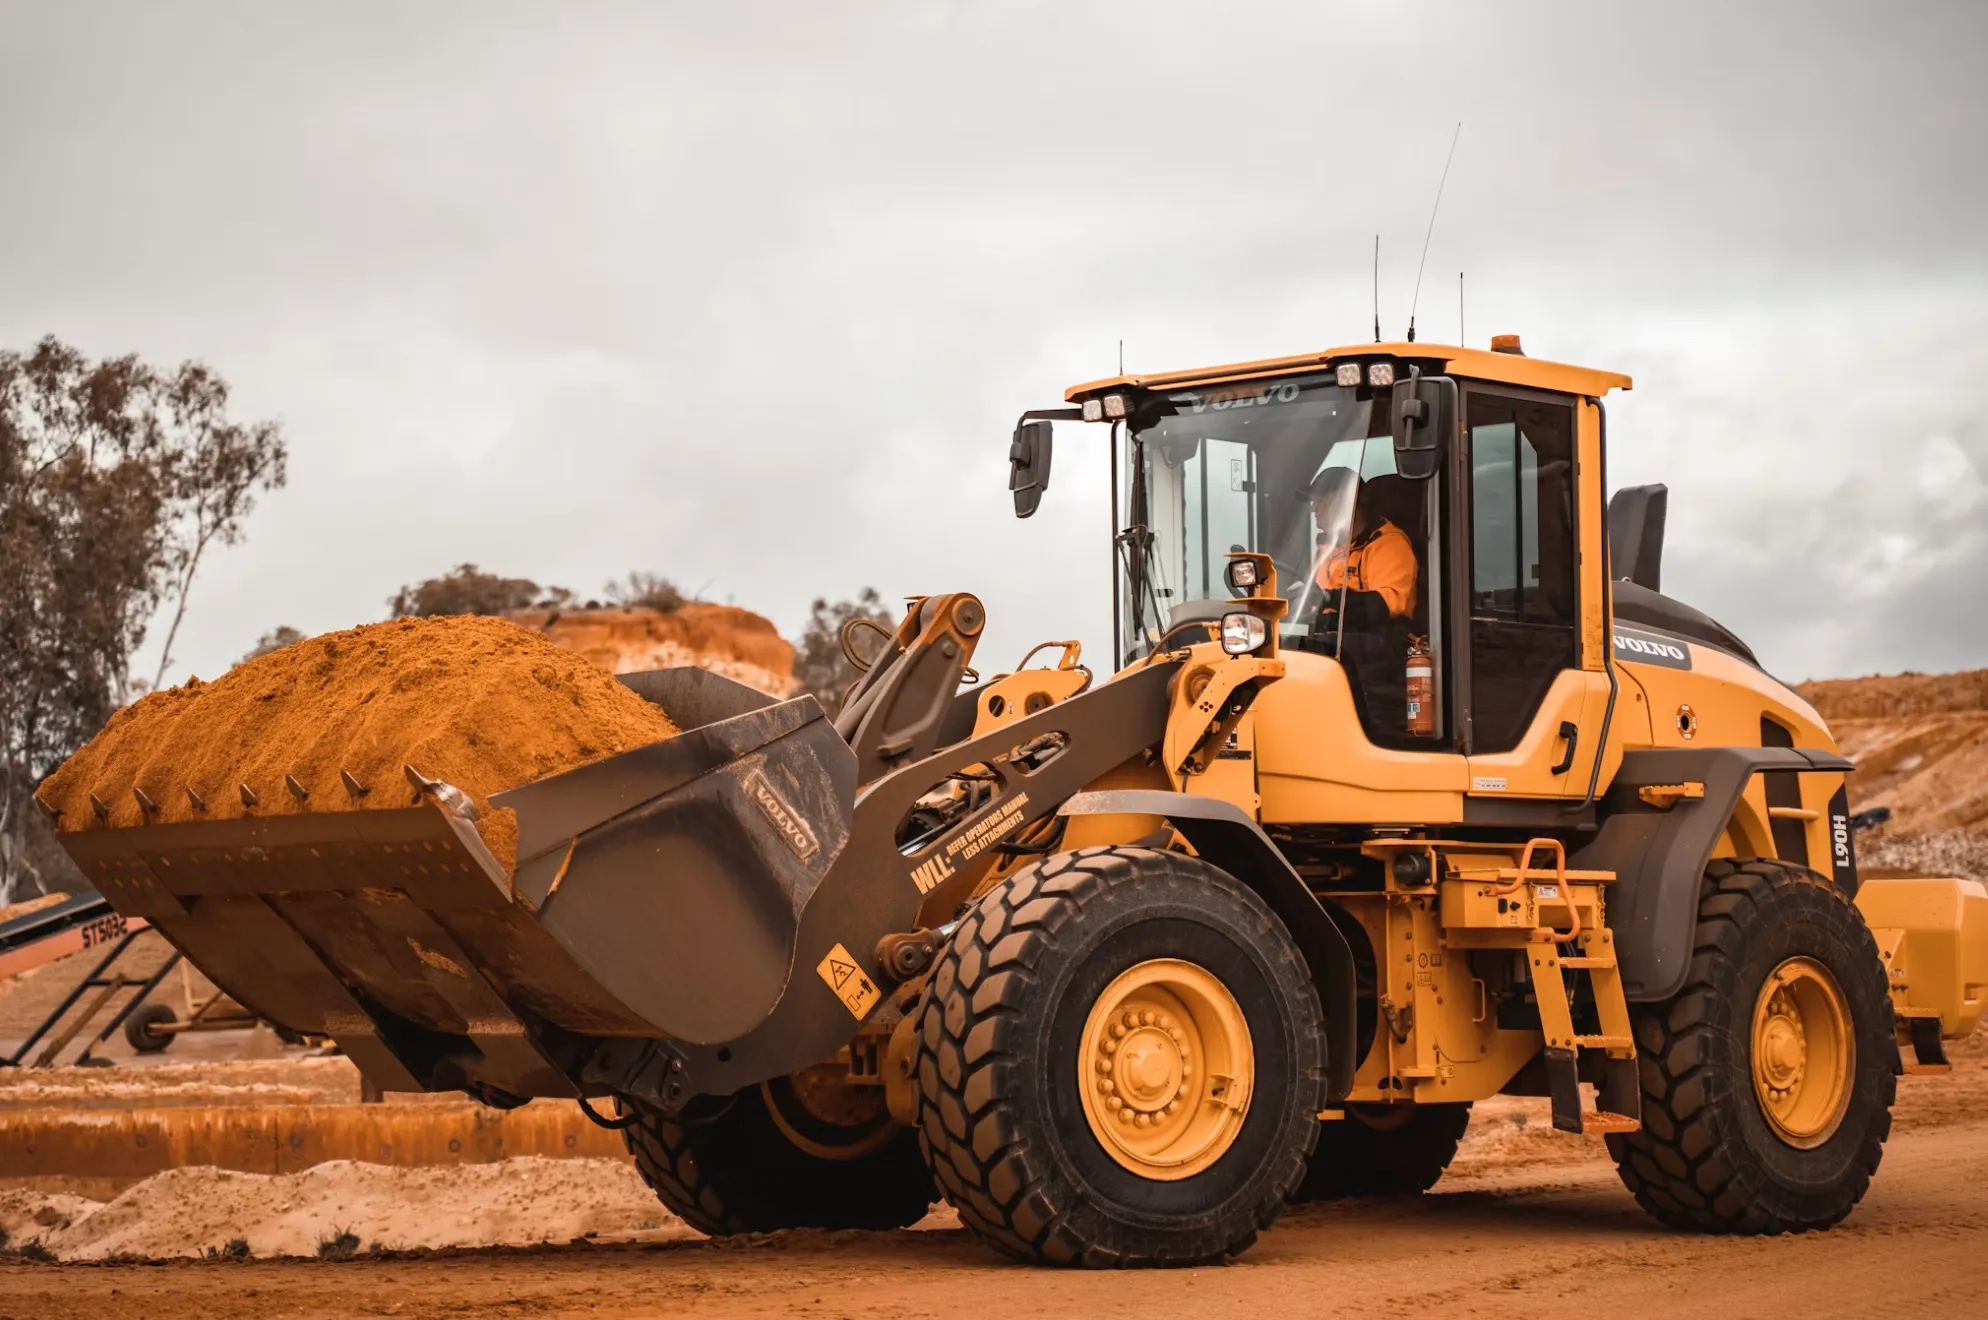
The rollover
An owner-operator's excavator rolls on a steep site. The machine is damaged and so is a neighbouring fence. Plant cover may apply to the machine and public liability to the fence, depending on the policy wording.
Understand the cover plant operators commonly use, what clients and sites ask for, and when it gets more complicated.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.
The short answer
Plant operators in Australia usually carry plant and equipment insurance for their machines, public liability insurance often to $20 million, and commercial motor cover for floats and trucks. Whether you hire machines out with an operator (wet hire) or without (dry hire), and where the machines work, are the biggest factors in what you need.
Common cover
Most plant operators build their insurance from a few separate policies. These are the ones that come up most, and why they matter for this kind of work.
Covers damage, overturning, fire and theft of excavators, loaders, rollers, cranes and attachments.
Covers damage to property and injury to people caused by your machines while working. Check how registered plant is treated.
Trucks and floats moving machines between jobs.
Owner-operators are usually not covered by workers compensation for their own injuries.
When it gets harder
A single owner-operator on residential jobs is relatively simple. These are the situations that change things.
Supplying a machine with your operator puts the operation on you. Dry hire puts it on the hirer, but you still own the machine. Each needs to be declared.
Mine sites set strict insurance, safety and machine standards, often with higher limits.
Lifting operations carry specific risks for the load being lifted, which standard policies may not cover.
Hiring extra machines for a big job puts you responsible for them. Your policy may need to cover hired-in plant.
Illustrative examples
These are illustrative examples, not real clients, showing how the work changes the insurance.
An owner-operator's excavator rolls on a steep site. The machine is damaged and so is a neighbouring fence. Plant cover may apply to the machine and public liability to the fence, depending on the policy wording.
A plant hire business is offered work on a mine site. The contract requires $20 million liability, specific machine standards and the mine operator noted on policies. Their policies need to be checked against each requirement.
Cost
These factors drive premiums for plant operators.
| Factor | Impact | Why it matters |
|---|---|---|
| Value and type of machines | Major | Larger and specialised machines cost more to insure. |
| Wet or dry hire | Major | The mix of hire types changes the liability picture. |
| Where machines work | Major | Mining, civil and residential sites are rated differently. |
| Operator experience | Moderate | Qualified, experienced operators are viewed favourably. |
| Claims history | Moderate | Previous damage and theft claims affect pricing. |
Common questions
Wet hire means you supply the machine and the operator, so you are responsible for how it is operated. Dry hire means the hirer operates it. Insurers treat them differently, so declare what you actually do.
Usually yes. Hire agreements generally make you responsible for the machine, and hire companies often ask for proof of cover.
Not necessarily. Damage to goods being lifted often needs specific cover, so check before taking on lifting work.
This page is general information only. It does not take into account your objectives, financial situation or needs, and it is not a recommendation to buy any insurance product. Always read the policy wording and, where applicable, the Product Disclosure Statement.
Request a quote
Tell us your trade or industry. It only takes a moment to get started.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.