The fibre strike
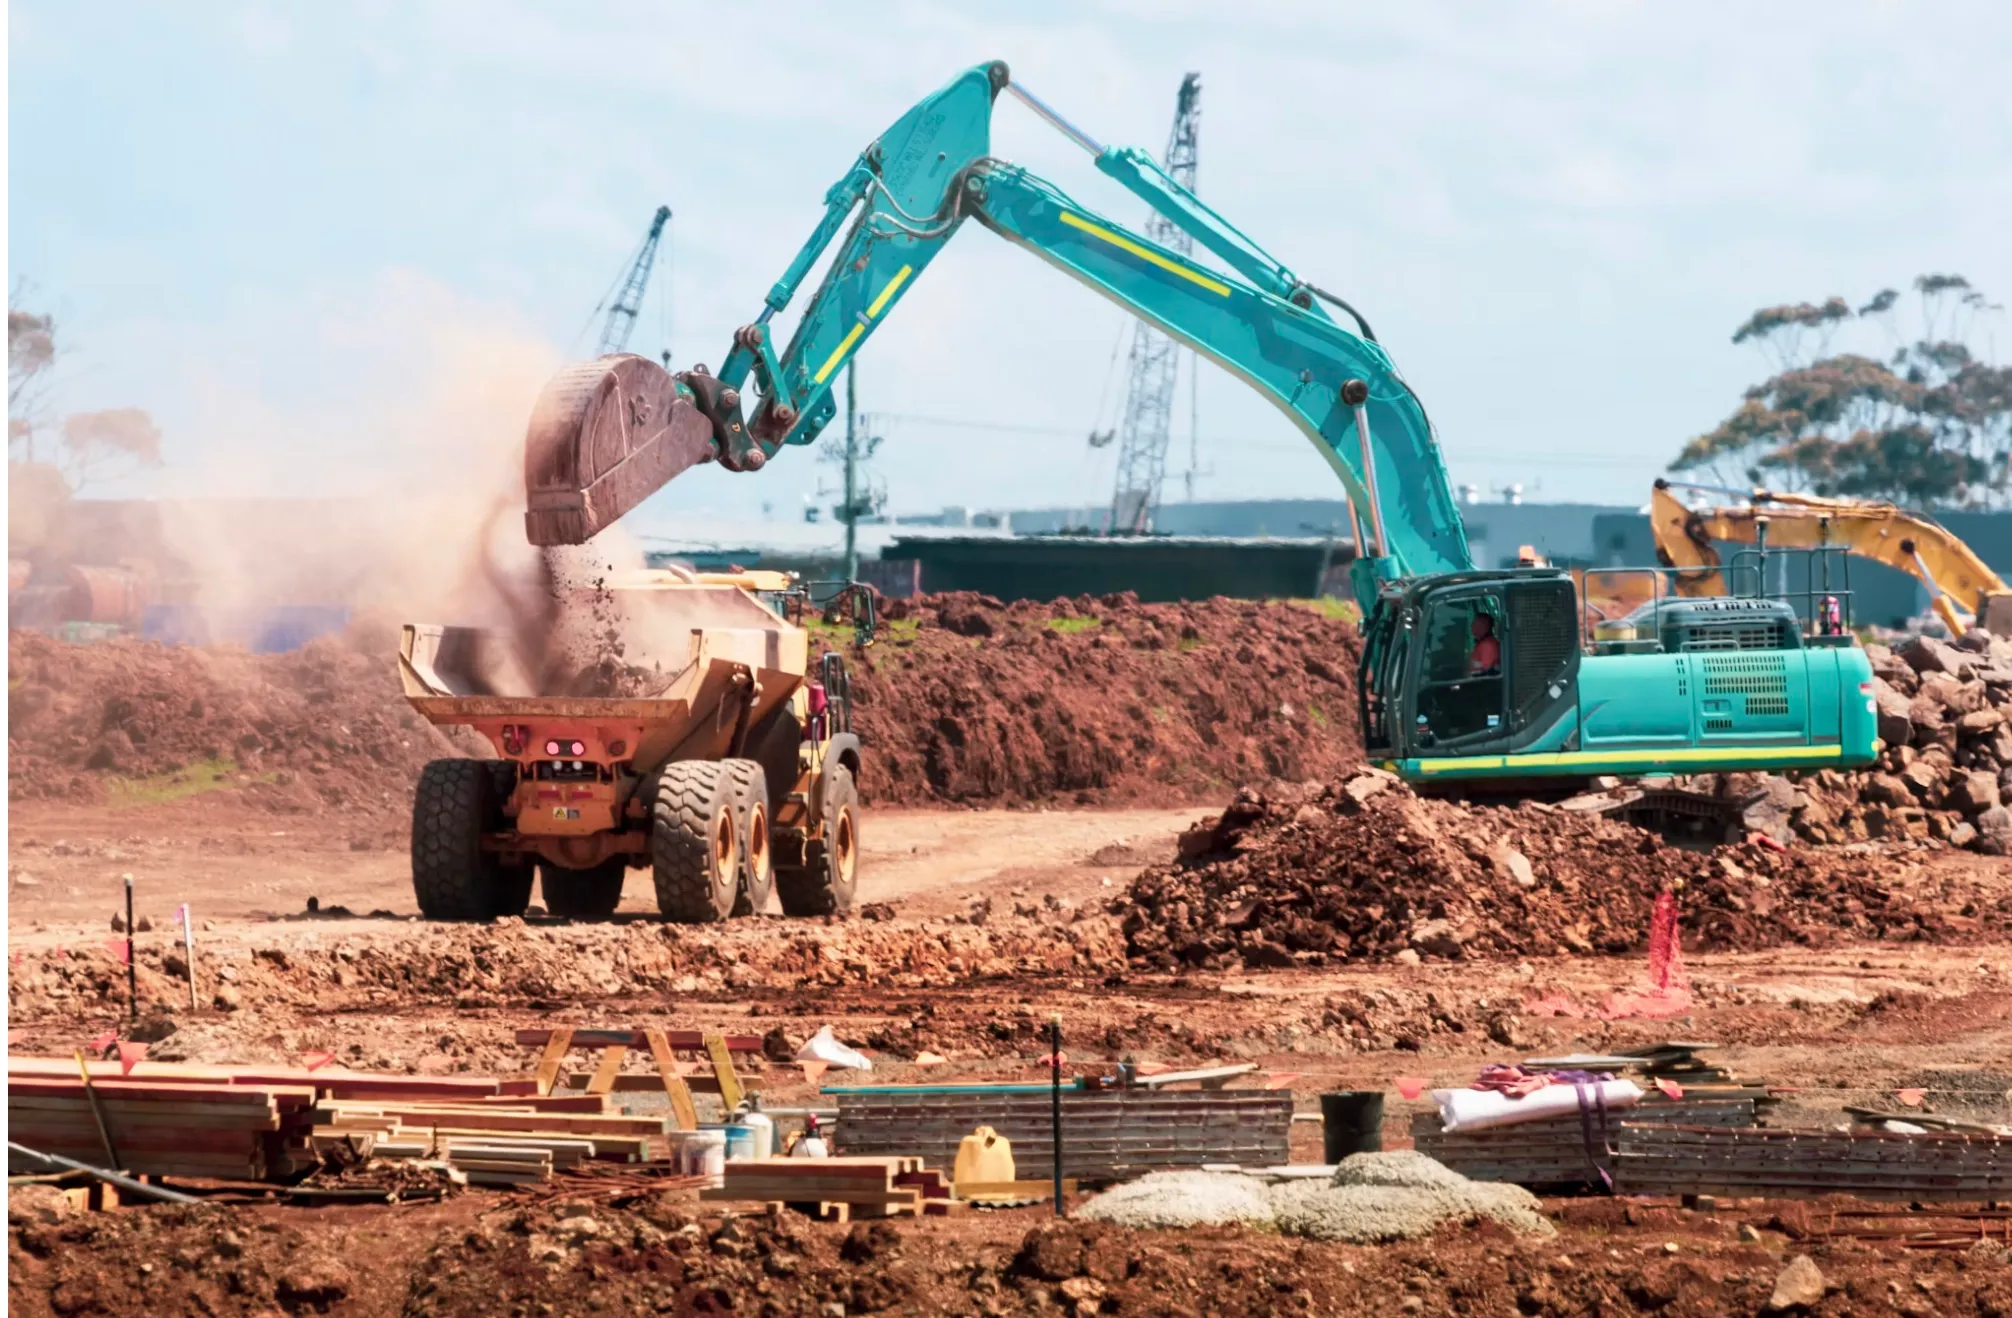
Trenching for a new driveway, an excavator operator cuts a fibre optic cable that wasn't marked on the plans. The telco's repair bill lands on the contractor, and the policy's underground services terms decide the excess.
Understand the cover earthmoving and civil contractors commonly use, what clients and sites ask for, and when it gets more complicated.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.
The short answer
Earthmoving and civil contractors in Australia usually carry public liability insurance, often $20 million, plant and equipment cover for machinery, commercial motor insurance for trucks and floats, and sometimes contract works. Damage to underground services is one of the most common and expensive claims, and infrastructure clients often set strict insurance requirements.
Common cover
Most earthmoving and civil contractors build their insurance from a few separate policies. These are the ones that come up most, and why they matter for this kind of work.
Covers damage to underground services, neighbouring property and third parties. Check excesses and sub-limits for underground services.
Excavators, loaders, rollers and attachments, whether owned, financed or hired in.
Tippers, floats, water carts and utes.
Civil contracts may require the works themselves to be insured.
When it gets harder
Digging is inherently risky, and civil clients are some of the most demanding when it comes to insurance.
Striking a fibre cable, water main or gas line can lead to large repair and consequential costs. Policies often have higher excesses or conditions about dial-before-you-dig checks.
Road, rail, water and energy projects commonly ask for $20 million or more, specific wording and principals noted on policies.
Hiring out machines with or without operators changes the risk. Policies need to reflect what you actually do.
Registered machines can fall between motor and liability cover while they're working. It is worth checking how your policies deal with that.
Illustrative examples
These are illustrative examples, not real clients, showing how the work changes the insurance.
Trenching for a new driveway, an excavator operator cuts a fibre optic cable that wasn't marked on the plans. The telco's repair bill lands on the contractor, and the policy's underground services terms decide the excess.
A small earthmoving business tenders for council drainage work. The tender requires $20 million liability, contract works and the council noted on policies. Their policies need to be checked against the tender before they submit.
Cost
These factors shape premiums for earthmoving and civil businesses.
| Factor | Impact | Why it matters |
|---|---|---|
| Type of civil work | Major | Residential site prep, roads, mining and infrastructure are rated very differently. |
| Plant fleet value | Major | The value and type of machines drives plant premiums. |
| Underground services exposure | Moderate | How much digging near services you do. |
| Turnover and operators | Moderate | More work and operators mean more exposure. |
| Claims history | Major | Service strikes and plant damage claims weigh heavily. |
Common questions
Usually, but often with a higher excess or a sub-limit, and sometimes with conditions such as checking service locations before digging. Check the wording carefully.
$20 million is common, and infrastructure, government and mining contracts can ask for more. The tender or contract documents set the requirement.
It depends on whether your policy covers dry or wet hire. Many plant policies need hire-out activities declared.
This page is general information only. It does not take into account your objectives, financial situation or needs, and it is not a recommendation to buy any insurance product. Always read the policy wording and, where applicable, the Product Disclosure Statement.
Request a quote
Tell us your trade or industry. It only takes a moment to get started.
Request a quote
Submitting this form does not arrange insurance. We'll use your details to help progress your enquiry.